
Income - Fixed interest selective
Income in a higher-rate world
Traditional bond funds were built for falling rates. In a world of higher rates, floating rate credit pays more as rates rise and gives the portfolio dry powder for opportunities.
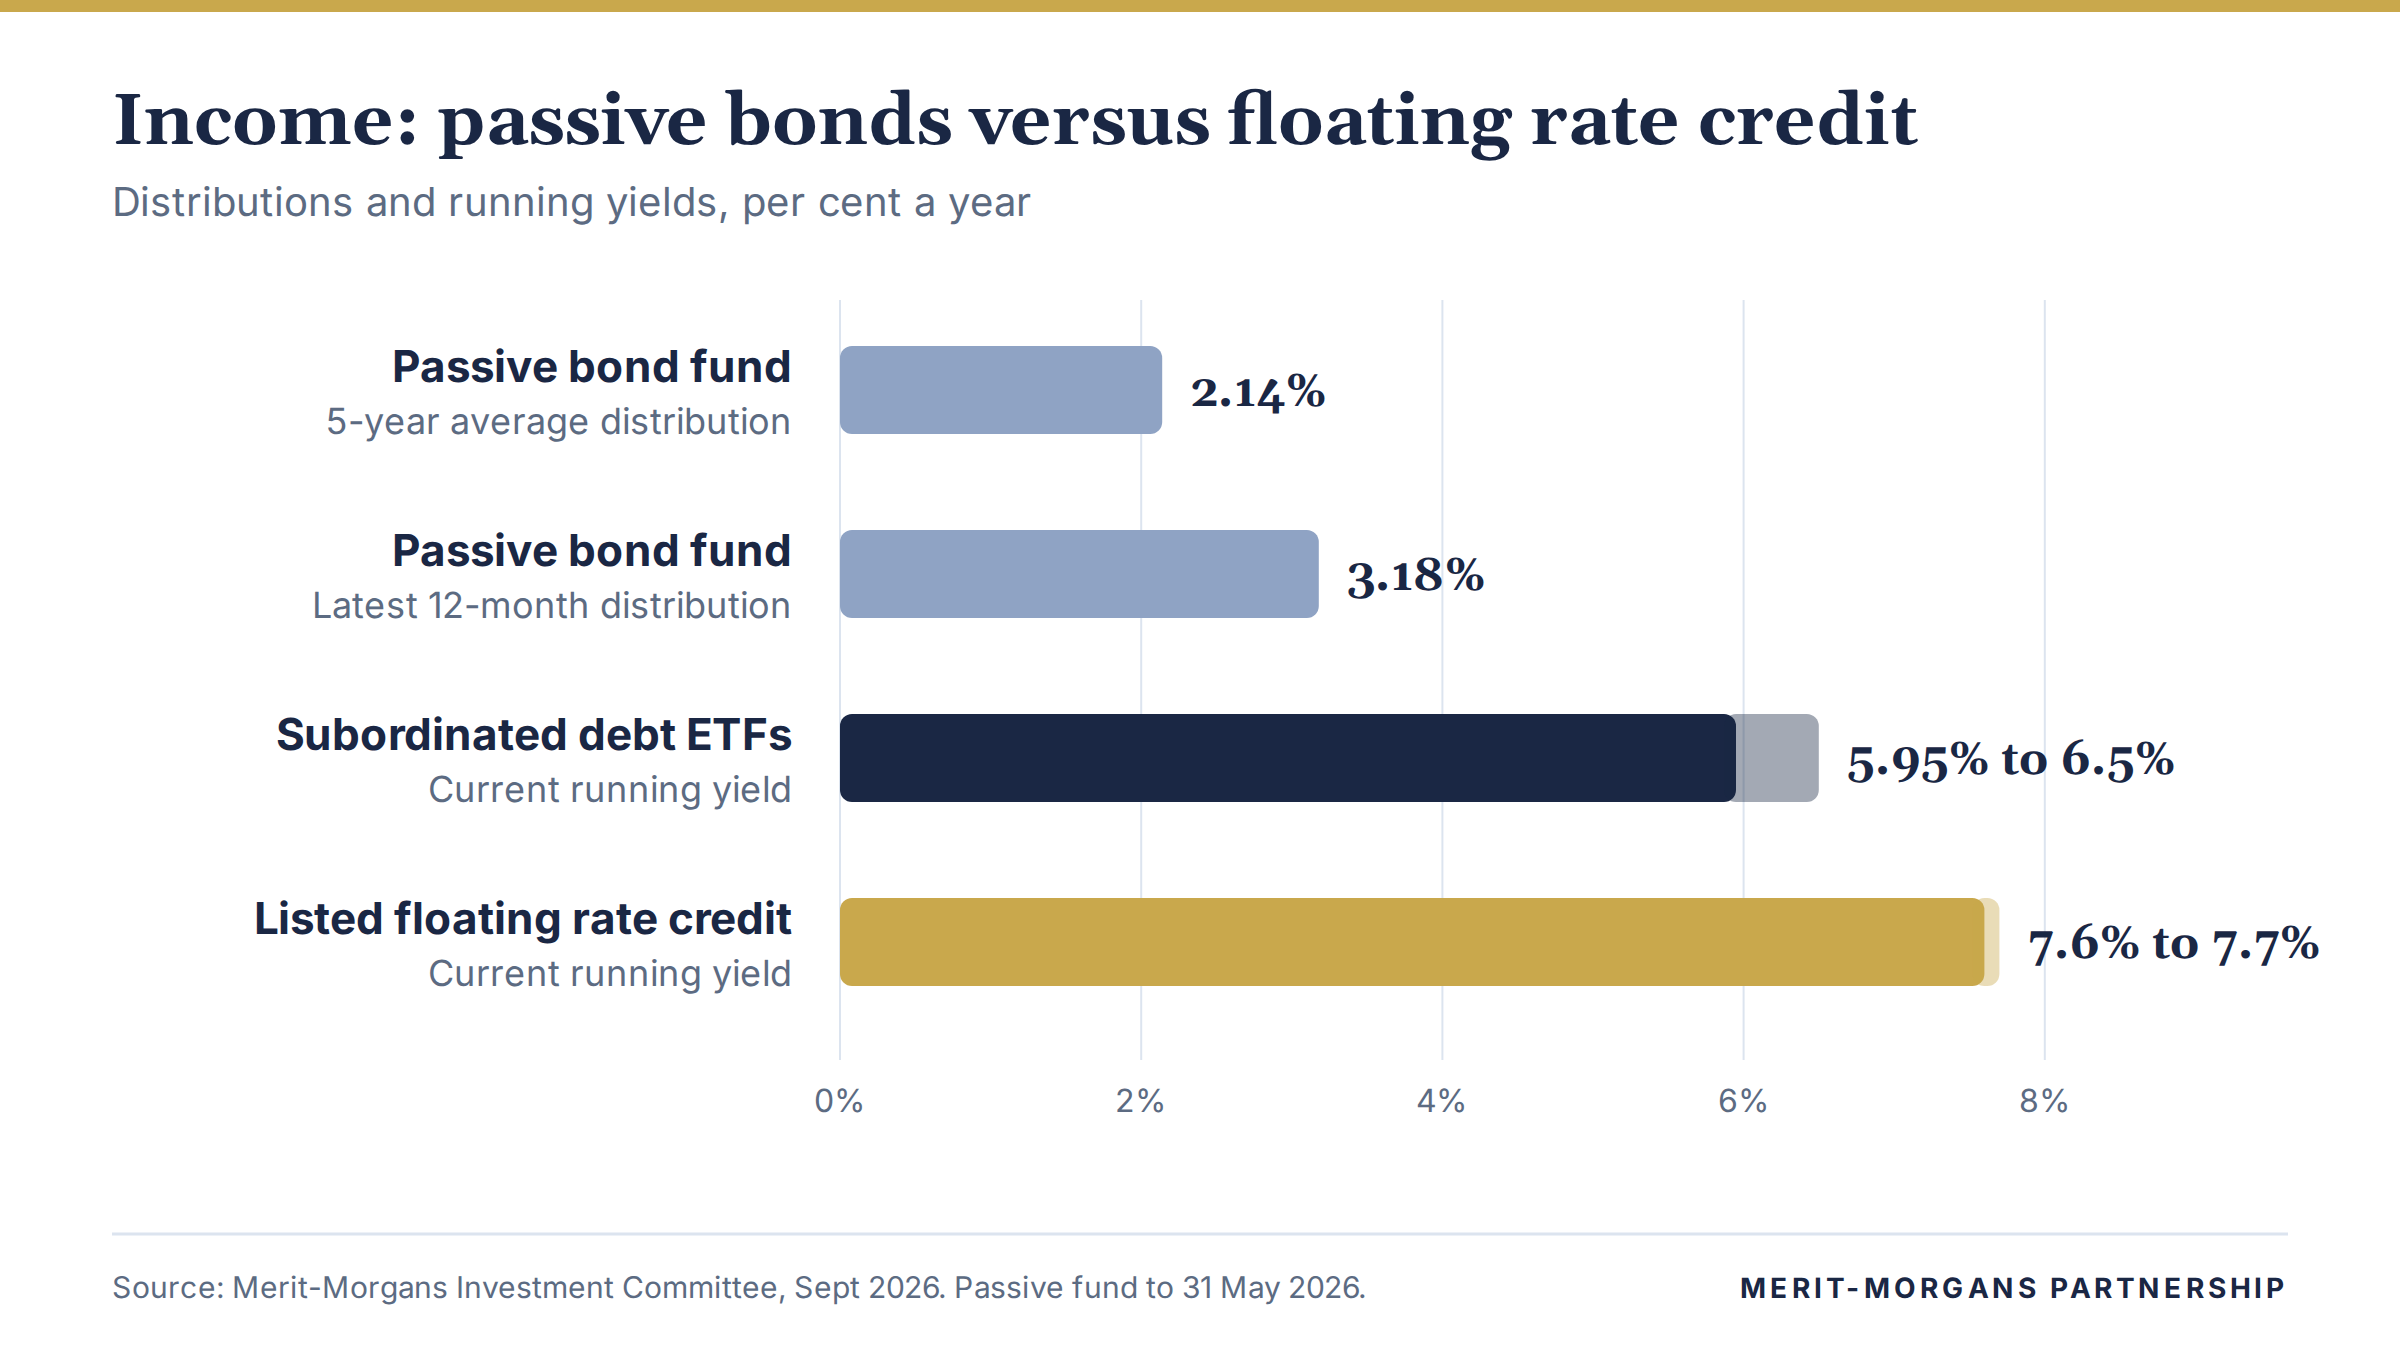
Large super funds typically hold most of their fixed interest in fixed rate government and high grade bonds. When rates rise, those bonds fall in price, and a broad passive Australian bond fund has not beaten inflation for more than a decade. Australian 10 year bond yields are now at 15 year highs, and this cycle has shown that bonds do not always cushion a fall in shares. When the worry is inflation or government borrowing, both can fall together.
Merit portfolios take a different approach. Defensive money sits in floating rate credit: subordinated bank debt, and listed credit trusts that lend to Australian businesses and residential borrowers. Their income resets with interest rates, so when rates rise the income rises too.
Why subordinated debt matters
- Defensive income that grows as rates rise, without the price falls fixed rate bonds suffer.
- Exposure to Australian bank Tier 2 debt with defined call and maturity dates at $100.
- Deep daily liquidity, so it can be sold at short notice to fund opportunities when markets fall.
That last point is the one that matters most. When the next correction comes, the portfolios can move money from this defensive allocation into quality growth assets at lower prices, rather than sitting in cash earning less.
Private credit headlines
Private credit is going through a stress testing phase, not a collapse. The pressure in the headlines is concentrated in property development lending, and much of the listed credit used in client portfolios does not lend to property development at all. Manager selection is what matters most, and the managers used have senior secured lending, diversified loan books and experience through downturns. Where quality listed credit trades below its asset backing, it is an opportunity to buy a higher yield.
How is your portfolio positioned?
Merit clients can talk through these themes at their next review. Call 1300 827 439 or email jim@meritfp.com.au.
More from the September update
- Built for the world we are entering
- Energy security: a structural shift, not a trade
- The biggest capex boom in history
- Where the earnings are
- Sophisticated investor status: what it opens up
This information is general advice only. It has been prepared without taking into account your objectives, financial situation or needs, so before acting on it you should consider whether it is appropriate for you and speak with your adviser. Past performance is not a reliable indicator of future performance. Forecasts are estimates by third parties and may not be achieved. Views are those of the Merit-Morgans Partnership Investment Committee and are current at the date of publication. Merit Financial Services Pty Ltd is a Corporate Authorised Representative (No. 416822) of Paragem Pty Ltd, AFSL 297276. Unit 41/280 New Line Road, Dural NSW 2158. Research, dealing and administration are provided by Morgans Financial Limited, ABN 49 010 669 726, AFSL 235410. Financial Services Guide.